
Here are three ready-to-use lean benefit package examples you can adapt today, organized by budget and headcount.
Starter Package (1–10 employees, roughly $150–$250/month per employee)
- QSEHRA reimbursement up to applicable IRS annual caps (employees buy their own individual coverage)
- SIMPLE IRA with a low employer match
- 10 days PTO plus federal holidays
- Flexible scheduling or remote-work option
- Best for: Bootstrapped businesses or early-stage startups that cannot yet afford group premiums
Competitive Package (10–49 employees, roughly $400–$650/month per employee)
- ICHRA or small-group health plan via broker, paired with an HSA contribution
- Section 125 cafeteria plan for pre-tax employee payroll deductions
- SIMPLE IRA or 401(k) with moderate employer match
- 15 days PTO plus sick leave
- Telehealth membership (e.g., Chameleonhc employer plan)
- Best for: Growing companies competing for experienced hires who expect real health coverage
Standout Package (25–99 employees, roughly $800–$1,200/month per employee)
- Small-group health plan with employer paying a majority of premiums, plus HSA seed contribution
- Section 125 cafeteria plan covering medical, dental, vision, and dependent care FSA
- 401(k) with employer match and immediate vesting
- 20 or more days PTO, parental leave, and flexible/hybrid scheduling
- EAP (Employee Assistance Program) and telehealth membership
- Best for: Companies in competitive hiring markets or industries with high turnover risk
Delivery method matters as much as the inclusions. A QSEHRA costs far less to administer than a group plan, but it shifts the coverage-shopping burden to employees. An ICHRA gives more flexibility on contribution amounts. A PEO bundles administration but adds per-employee fees. The right choice depends on your headcount, HR bandwidth, and how much hands-on support your team needs.
Key Takeaways
A focused, tiered lean benefits package built around health access, retirement, and flexibility delivers more perceived value per dollar than a long menu of low-use perks.
| Point | Details |
|---|---|
| Start with three tiers | Starter, Competitive, and Standout packages give you a ready framework to match your headcount and budget. |
| Prioritize health, retirement, and flexibility | HBR research shows these three categories are more persuasive to candidates than a pay increase. |
| Use Section 125 and HSAs early | Implementing Section 125 first, then adding an HSA/HDHP, is the most tax-efficient sequence for small employers. |
| Add telehealth for immediate visible value | A telehealth membership at $20–$40/month per employee is the highest-ROI addition to any lean package. |
| Chameleonhc for employer telehealth | Chameleonhc’s employer plans offer same-day virtual care with transparent pricing and no insurance required. |
Table of Contents
- Why do lean benefit packages outperform large-company menus?
- What are the core components of a lean benefit plan?
- Sample lean packages by budget tier
- How should you deliver benefits: PEOs, group plans, ICHRA, and more?
- How to implement a lean benefits package step by step
- Key U.S. legal and tax notes that affect lean package design
- How does telehealth fit into a lean benefits package?
- How do you measure and communicate the value of a lean package?
- What a lean package actually looks like in practice
- Chameleonhc makes telehealth easy to add to any lean package
- Sources
Why do lean benefit packages outperform large-company menus?
The instinct to copy a Fortune 500 benefits menu is understandable, but it rarely serves small employers well. A long list of low-use perks dilutes your budget across things most employees never touch. A focused package concentrates spend on the two or three benefits employees actually value, which creates stronger perceived value per dollar.
Harvard Business Review research confirms what many HR professionals already sense: flexible work, better health coverage, and time off are more persuasive in recruiting than a pay increase for a significant share of workers. That finding points directly to a lean strategy. You do not need a gym subsidy, a pet insurance option, and a commuter benefit to win candidates. You need health access, schedule control, and a retirement path.
There is also an operational argument. Predictable costs are easier to budget. Simpler plans are easier to explain during onboarding. And a package with three strong components scales more cleanly than one with twelve marginal ones. When you add a new hire, you add one person to a system that already works, avoiding managing many vendor relationships.
Research on lean practices more broadly suggests that lean changes work best when they are paired with supportive structures that protect employee wellbeing, rather than simply cutting resources. The same logic applies here: a lean benefits package is not about removing support. It is about removing waste and redirecting that spend toward what employees actually use.
Pro Tip: Run a two-question pulse survey before you finalize your package. Ask employees to rank their top two benefit priorities from a short list (health, retirement, PTO, flexibility, mental health). The results almost always reveal that two or three items dominate, and that data gives you a defensible rationale for your choices.
What are the core components of a lean benefit plan?
Each component below serves a different function in the total compensation picture. The right mix depends on your size, workforce profile, and budget shape.
| Component | What it is | When to use it | Admin complexity |
|---|---|---|---|
| QSEHRA | Tax-free HRA for employers with fewer than 50 employees; reimburses individual health premiums and medical expenses up to IRS caps | Best for very small employers who cannot afford group premiums | Low |
| ICHRA | Individual Coverage HRA with no contribution cap; employees buy their own coverage and get reimbursed | Fits employers of any size who want flexibility on contribution amounts | Low–Medium |
| Small-group health plan | Employer-sponsored group insurance purchased via broker or SHOP marketplace | Best when you have 10+ employees and want to offer a defined plan | Medium–High |
| HSA | Employee-owned savings account paired with a High-Deductible Health Plan (HDHP); triple tax advantage | Pair with any HDHP-compatible plan; great for cost-conscious employees | Low |
| Section 125 cafeteria plan | IRS-approved plan letting employees pay premiums and FSA contributions pre-tax via payroll | Use alongside any health or FSA offering to reduce payroll taxes for both employer and employee | Low–Medium |
| SIMPLE IRA | Employer-sponsored retirement plan with mandatory employer contributions; easy to set up | Best for employers with fewer than 100 employees who want a low-cost retirement option | Low |
| SEP IRA | Employer-only contributions; simpler than a 401(k) but less flexible for employees | Good for sole proprietors or very small teams with variable revenue | Low |
| 401(k) | Standard employer retirement plan with employee deferrals and optional employer match | Best once you have 20+ employees or are competing for experienced talent | Medium–High |
| PTO / flexible scheduling | Paid time off, sick leave, and schedule flexibility | Every package; BLS benchmarking data helps you set competitive PTO levels by industry | Low |
| EAP | Employee Assistance Program providing mental health counseling, financial coaching, and crisis support | Add to Competitive or Standout tiers; low cost, high perceived value | Low |
| Telehealth membership | Employer-paid virtual care access for common conditions, often without insurance | Fits every tier; especially high ROI for remote or distributed teams | Low |
A few components deserve a closer look when you are building your first package. The QSEHRA is a practical option for small employers who cannot afford a group plan. Nimble Advisors recommends QSEHRA specifically for employers who cannot offer a group plan, paired with a SIMPLE IRA as a retirement starter. That combination covers the two highest-priority benefit categories (health and retirement) at a fraction of the cost of a traditional group plan plus 401(k).
Flexible scheduling and remote work deserve a spot on every list. They cost the employer little to nothing, yet they consistently rank among the highest-valued perks in employee satisfaction surveys. If your business model allows it, offering schedule control is one of the most efficient benefits decisions you can make.
Sample lean packages by budget tier
The three tiers below expand on the opening examples with enough detail to use as a starting template. Cost estimates are employer-side only and assume a healthy mix of ages; actual premiums vary by state, carrier, and workforce demographics.
Starter tier: 1–10 employees
Estimated employer cost: $150–$250/month per employee, depending on QSEHRA reimbursement level set.
Admin complexity: Low. QSEHRA requires a written plan document and annual notice to employees, but no carrier relationship. SIMPLE IRA setup through Fidelity, Vanguard, or a similar provider takes a few hours.
Scalability: Works well up to about 15 employees. Beyond that, a group plan or ICHRA often becomes more cost-competitive.
Employee perceived value: Moderate. Employees appreciate the health reimbursement and retirement match, but the lack of a defined plan can feel less tangible than a group insurance card.
Optional add-on: A telehealth membership at $20–$40/month per employee adds immediate, visible health access without the complexity of a group plan.
Competitive tier: 10–49 employees
Core inclusions: ICHRA or small-group HDHP paired with an employer HSA seed contribution ($500–$1,000/year), Section 125 cafeteria plan, SIMPLE IRA or 401(k) with moderate employer match, 15 days PTO, telehealth membership.
Estimated employer cost: $400–$650/month per employee. Pegacorn Group’s analysis of startup benefits stacks shows health, retirement, and parental leave are the highest-utilization components, which is where this tier concentrates spend.
Admin complexity: Medium. Section 125 requires a plan document and annual nondiscrimination testing. An ICHRA needs a written plan and integration with payroll. A group plan adds a carrier relationship and open enrollment management.
Scalability: Designed to grow with you. The Section 125 and HSA structure scales per-employee without redesigning the plan.
Employee perceived value: High. A real health option plus a retirement match plus schedule flexibility covers the top three priorities most employees name.
BenefitsGenius recommends implementing Section 125 first, then adding an HSA/HDHP and voluntary benefits, as the most tax-efficient sequence for startups. That sequencing keeps employer cash outlays lower while building meaningful total compensation.
Standout tier: 25–99 employees
Estimated employer cost: $800–$1,200/month per employee, with health premiums as the largest variable.
Admin complexity: Medium–High. Multiple vendor relationships, annual open enrollment, and 401(k) plan administration require either a dedicated HR person or a PEO.
Scalability: Strong. The 401(k) and group plan infrastructure supports growth past 100 employees with modest adjustments.
Employee perceived value: Very high. This package competes directly with mid-size company offerings and is a genuine recruiting differentiator in tight labor markets.
Where to spend an incremental dollar: If you are already at the Standout tier, adding parental leave or a student loan repayment benefit tends to produce the highest retention lift among employees under 40.
How should you deliver benefits: PEOs, group plans, ICHRA, and more?
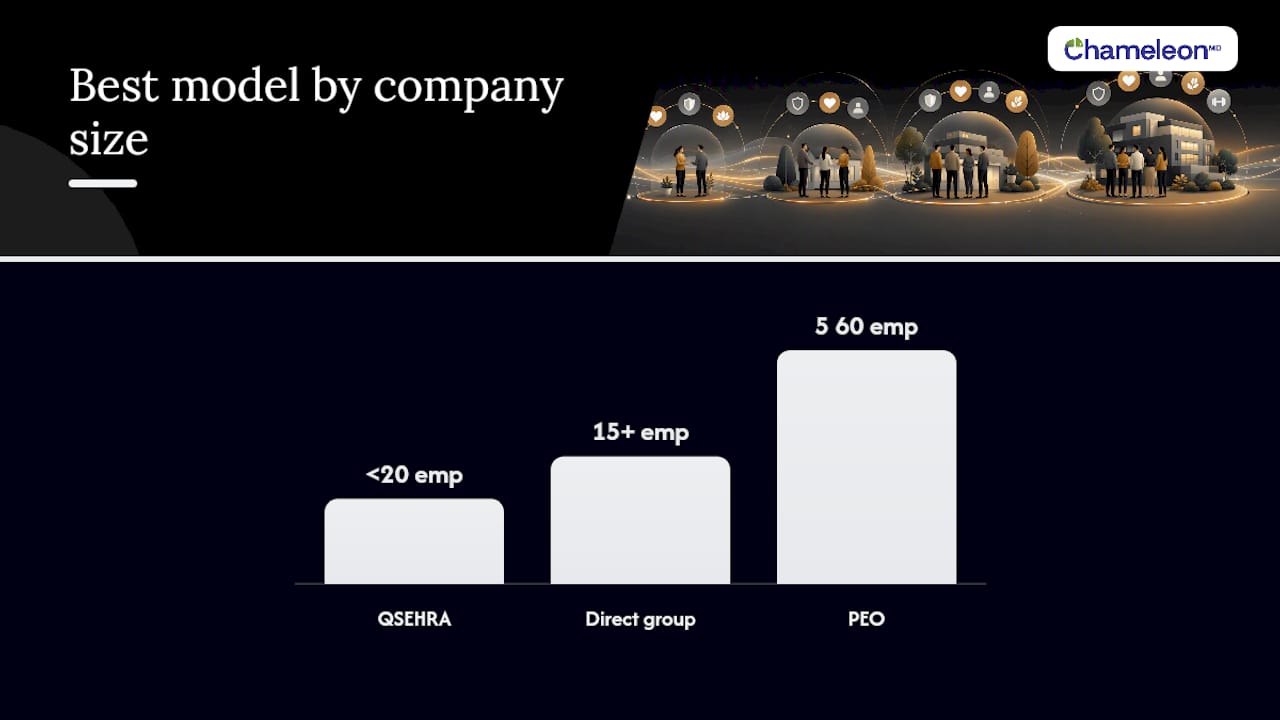
Your delivery model determines your administrative workload, your compliance exposure, and often your per-employee cost. Choose based on headcount and how much HR bandwidth you actually have.
PEO (Professional Employer Organization)
- Co-employs your staff and handles payroll, benefits administration, and compliance
- Access to large-group health rates even with a small team
- Adds per-employee fees ($80–$200/month typically) on top of benefit costs
- Best for: 5–50 employees with no dedicated HR staff
Direct group plan via broker
- You select a carrier and plan design; a broker handles enrollment and renewals
- More control over plan design than a PEO
- Requires someone internally to manage open enrollment and employee questions
- Best for: 15+ employees with at least part-time HR support
ICHRA
- Employer sets a monthly reimbursement amount; employees buy their own ACA-compliant individual coverage
- No contribution cap; works for employers of any size
- Employees must have qualifying individual coverage to receive reimbursements
- Best for: Remote or geographically distributed teams where a single group plan covers no one’s preferred network
QSEHRA
- Similar to ICHRA but capped at IRS annual limits and restricted to employers with fewer than 50 employees
- Simpler to administer than a group plan; requires a written plan document and annual employee notice
- Cannot be offered alongside a group health plan
- Best for: Very small employers (under 20 employees) who want to offer health support without a carrier relationship
Cash stipends
- Employer pays a taxable monthly stipend for health, wellness, or professional development
- Zero compliance complexity, but the stipend is taxable income to the employee
- Best for: Employers who want maximum simplicity and are comfortable with the tax treatment
Section 125 cafeteria plan
- Lets employees pay premiums, FSA contributions, and dependent care costs pre-tax via payroll deduction
- Reduces FICA taxes for both employer and employee
- Requires a written plan document; annual nondiscrimination testing applies
- Best for: Any employer offering health or FSA benefits who wants to reduce payroll tax costs
A simple recommendation: if you have fewer than 10 employees and no HR staff, start with a QSEHRA and a SIMPLE IRA. At 10–30 employees, add a Section 125 plan and consider an ICHRA or small-group HDHP. Past 50 employees, a direct group plan or PEO typically becomes the most cost-effective route. You can find a detailed affordable healthcare plan comparison that walks through QSEHRA, ICHRA, and SHOP options side by side.
How to implement a lean benefits package step by step
The short version: decide your budget, pick your delivery model, set up payroll and communications, then enroll. Here is the full sequence.
- Run a two-question employee preference survey (1 week). Ask employees to rank their top two benefit priorities. Use the results to confirm your tier choice and avoid spending on low-demand perks.
- Model costs (1 week). Use your chosen tier’s cost estimates as a starting point. Factor in your state’s small-group premium rates if you are considering a group plan. Get a QSEHRA or ICHRA quote from a platform like Take Command Health or PeopleKeep if you are going the HRA route.
- Select your delivery model and vendors (2–3 weeks). Choose between PEO, direct broker, ICHRA/QSEHRA platform, or a combination. For retirement, contact Fidelity, Vanguard, or a SIMPLE IRA provider. For telehealth, evaluate employer membership options.
- Draft and execute plan documents (1–2 weeks). A Section 125 plan requires a written plan document before the plan year starts. A QSEHRA requires a written notice to employees at least 90 days before the plan year (or before the plan starts for new employers). An ICHRA requires a written plan document and a 90-day notice period before the plan year.
- Set up payroll coding (1 week). Work with your payroll provider (Gusto, Rippling, ADP, or similar) to code pre-tax deductions correctly under Section 125. Confirm that QSEHRA or ICHRA reimbursements are coded as non-taxable.
- Enroll employees and launch communications (1–2 weeks). Send a clear, one-page benefits summary. Hold a 30-minute Q&A session. Provide a simple FAQ document covering how to use each benefit.
- Set a 90-day check-in (ongoing). Review enrollment rates and any early utilization data. Adjust communications if participation is lower than expected.
Pro Tip: If you are setting up a Section 125 plan for the first time, your payroll provider can often generate the required plan document for a small fee or include it as part of their HR add-on. Gusto and Rippling both offer this. It saves you the cost of a standalone benefits attorney for a basic plan.
Key U.S. legal and tax notes that affect lean package design
A few rules materially change what you can offer and how you structure it. These are the ones worth knowing before you finalize any package.
- QSEHRA caps: The IRS sets annual contribution limits for QSEHRAs which adjust annually for inflation; employers should check the current year’s figures on the IRS website. Employers with fewer than 50 employees who offer a QSEHRA cannot simultaneously offer a group health plan. FirstHR’s small business benefits guide covers the QSEHRA structure and its practical limits in detail.
- ICHRA rules: No contribution cap, but employees must have qualifying individual coverage (ACA marketplace or off-exchange). ICHRA can be offered alongside a group plan to different classes of employees, but the classes must be defined in the plan document.
- HSA eligibility: Employees can only contribute to an HSA if they are enrolled in an IRS-qualified HDHP and have no other disqualifying coverage. For 2026, the IRS sets minimum deductible and out-of-pocket maximum thresholds for HDHPs. HSAs offer a triple tax advantage: contributions are pre-tax, growth is tax-free, and qualified withdrawals are tax-free.
- Section 125 basics: A written plan document is required before the plan year starts. The plan must pass annual nondiscrimination testing to confirm it does not disproportionately benefit highly compensated employees. Failure to pass testing can result in benefits becoming taxable for key employees.
- ACA employer mandate: Employers with 50 or more full-time equivalent employees (Applicable Large Employers, or ALEs) must offer minimum essential coverage that meets affordability standards or face potential penalties. Employers with fewer than 50 FTEs are not subject to the mandate, though offering coverage still carries recruiting and retention value.
- Retirement plan deadlines: A SIMPLE IRA must be established by October 1 of the year it will take effect for existing businesses. A SEP IRA can be set up as late as the employer’s tax filing deadline, including extensions.
For state-specific rules (state income tax treatment of HRA reimbursements, state-mandated benefits, or state-level ACA requirements), consult a benefits attorney or CPA familiar with your state. The IRS and Department of Labor websites are the primary sources for federal compliance guidance.
How does telehealth fit into a lean benefits package?
Telehealth memberships deliver some of the highest perceived value per employer dollar of any benefit in a lean package. Employees get same-day access to a licensed provider for common conditions (sore throat, sinus infection, rash, UTI) without taking half a day off work. For employers, that translates directly to less absenteeism and fewer productivity gaps.
Workplace health research indexed on PMC supports adding mental health access and telehealth-style services as effective interventions for employee wellbeing. The practical mechanism is straightforward: when care is easy to access, employees use it earlier, before a minor issue becomes a multi-day absence.
Here is how to add telehealth to a lean package without overcomplicating it:
- Standalone employer subscription: The employer pays a flat monthly fee per employee for a telehealth membership. No insurance required. Employees get a login and can connect with a provider the same day. This is the simplest route and works at every tier.
- Section 125 pre-tax payroll: If employees contribute to the cost, run those contributions through a Section 125 plan so they are pre-tax. This reduces the net cost for both the employee and the employer.
- Bundled with an HRA: Pair a QSEHRA or ICHRA with a telehealth membership so employees have both reimbursement support for larger expenses and immediate access for everyday care needs.
Chameleonhc fits naturally into the Starter and Competitive tiers as the telehealth component. It offers employer-sponsored telehealth with transparent pricing, same-day virtual visits, and no insurance requirement. For remote or hybrid teams where a single group plan may not cover everyone’s preferred providers, a telehealth membership fills the gap in a way that is easy to communicate and easy to use.
Pro Tip: When you introduce telehealth to your team, lead with a concrete use case: “If you wake up with a sore throat on a Monday morning, you can see a provider before 9 AM from your phone.” That one sentence does more to drive utilization than a paragraph of feature descriptions.
How do you measure and communicate the value of a lean package?
A lean package only works if employees know about it and use it. Participation rates and utilization data tell you whether your spend is landing.
Metrics to track:
- Enrollment rate: What percentage of eligible employees enrolled in each benefit? A health enrollment rate below 70% usually signals a communication gap, not a design problem.
- HSA participation: Are employees contributing to their HSAs? Low HSA participation often means employees do not understand the tax advantage.
- Telehealth utilization: How many visits per employee per quarter? Low utilization typically responds well to a single reminder email with a concrete use case.
- Benefits NPS: Once a year, ask employees one question: “On a scale of 0–10, how likely are you to recommend our benefits package to a friend considering a job here?” A score above 7 is a strong signal. Below 5 means you have a communication or design problem worth addressing.
Simple communication template for recruiting:
Use a one-line benefits statement in job postings: “We offer health reimbursement, a retirement match, flexible scheduling, and same-day telehealth access.” That sentence covers the four categories HBR research identifies as most persuasive to candidates, without overpromising.
For internal launch communications, keep it to three bullets:
- What you now have access to (list each benefit with one sentence on how to use it)
- What it costs you (employee contribution, if any)
- How to enroll (one link, one deadline)
Early uptake data from the first 90 days is your best feedback loop. If telehealth utilization is low, send one targeted email with a specific scenario. If HSA enrollment is low, add a one-paragraph explainer on the tax math. Iteration based on real participation data is faster and cheaper than redesigning the package. The telemedicine HR guide covers how to communicate telehealth as a benefit in more detail.
What a lean package actually looks like in practice
The most common mistake I see small employers make is waiting until they can afford the “full” package before offering anything. The result is a year or two of recruiting at a disadvantage, losing candidates to competitors who offer even a modest QSEHRA and a SIMPLE IRA.
The change that tends to produce the most immediate impact is adding telehealth. It is visible, fast, and easy to explain. One small employer I am aware of added a telehealth membership at roughly $30/month per employee and saw it become the most-mentioned benefit in exit interviews and candidate conversations within two quarters. The health reimbursement and retirement match were appreciated, but telehealth was the one employees talked about because they actually used it.
The second insight worth holding onto: employees do not compare your package to an abstract ideal. They compare it to their last job and to what they hear from peers. You do not need to match a 500-person company’s benefits to win the candidates you want.
Iterate based on what employees use. If your HSA participation is low after six months, add a one-time employer seed contribution to make the value concrete. If telehealth utilization is high, consider upgrading to a plan that includes mental health visits. The package should evolve with your team, not sit static from year one.
Chameleonhc makes telehealth easy to add to any lean package
For small employers building a lean package, health access is the hardest piece to get right without overspending. Chameleonhc offers employer telehealth plans with transparent, upfront pricing and no insurance requirement. Your employees get same-day virtual visits for common conditions, from sore throats to sinus infections to rashes, all from their phone or computer.
It fits cleanly into Starter and Competitive tiers as a standalone telehealth line item, and it pairs naturally with a QSEHRA or ICHRA so employees have both reimbursement support and immediate care access. For remote or hybrid teams, it solves the coverage-gap problem that a single regional group plan often cannot. Visit Chameleonhc’s employer plans page to see current pricing and get your team set up.
Sources
These are the primary sources used in this article. Each one is worth bookmarking for ongoing compliance and benchmarking.
- The Series A/B benefits stack — Pegacorn Group
- Small business employee benefits — FirstHR
- The most desirable employee benefits — HBR
- BLS chart: paid leave, sick, vacation days
- Workplace health interventions — PMC
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.