
Expect to pay a moderate amount for a single self-pay telehealth visit, or a modest monthly fee (or an annual membership) for a membership plan. If you see a doctor virtually more than a few times a year, a membership generally saves you money over paying per visit. Medicare and many insurance plans can lower your share further, but the only way to know your exact number is to check your specific benefits before you book.
TL;DR:
- Paying a monthly membership is more cost-effective than pay-per-visit if you expect more than four virtual visits per year, especially when including medications and referrals.
- Telehealth visits typically cost between $40 and $50 nationally, significantly less than in-person visits which average around $136, but additional costs for tests and prescriptions are usually billed separately.
- Many telehealth memberships are month-to-month but some require annual commitments, with condition-specific plans often needing three to six months, making cancellation terms crucial to understand.
- Chameleon Healthcare offers transparent, upfront subscription plans covering primary and urgent care with no hidden fees, ideal for families and ongoing health management needs.
Table of Contents
- Telehealth Membership Cost: Comparing Pricing Models
- What Does Telehealth Cost Per Visit and Per Month?
- Does Insurance or Medicare Cover Telehealth Visits?
- How Do You Choose the Right Telehealth Pricing Plan?
- How Chameleon Healthcare’s Membership Changes the Cost Equation
- How Long Do You Have to Commit to a Telehealth Membership?
- What Happens When You Cancel a Telehealth Membership?
- How Do Telehealth Membership Costs Compare Across Providers?
- When Membership Actually Pays Off
- Chameleon Healthcare Plans: Where to See Real Pricing
- Sources
Telehealth Membership Cost: Comparing Pricing Models
Not every telehealth plan bills you the same way, and understanding the difference is what actually helps you avoid overpaying. Four models dominate the market right now, and each one fits a different kind of patient.
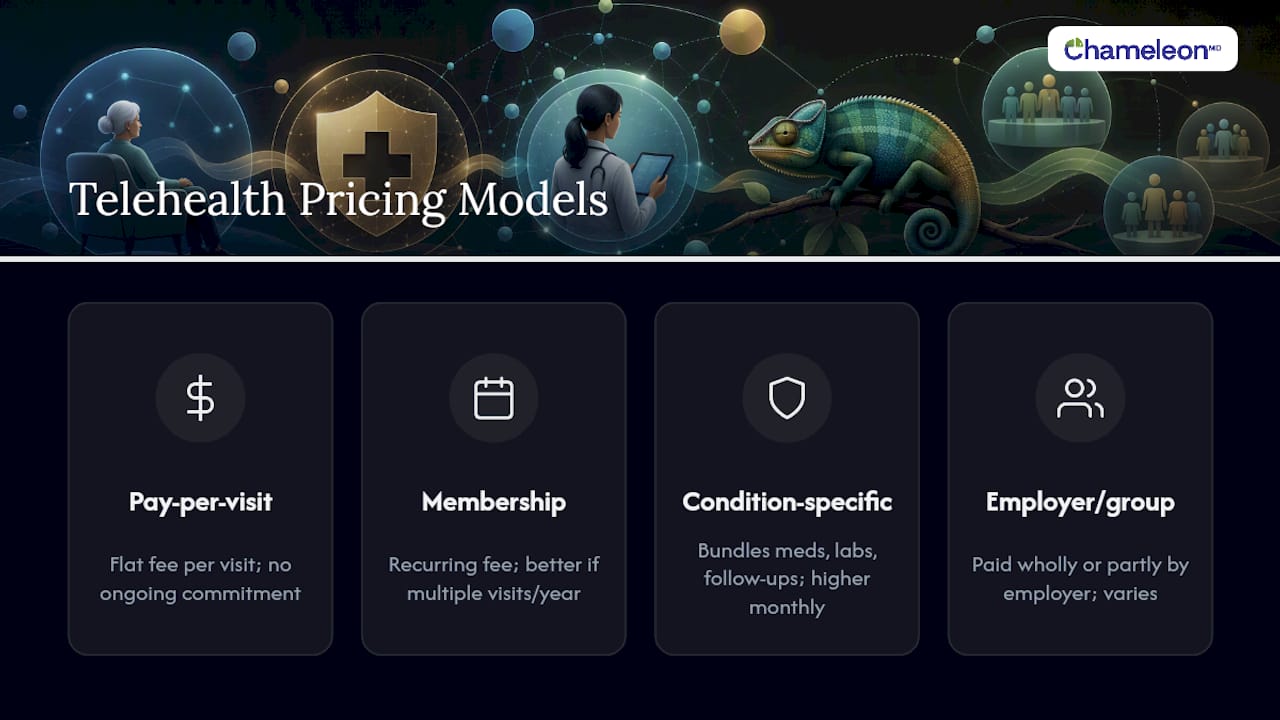
Pay-per-visit works like an urgent care copay without the waiting room. You pay a flat fee each time you connect with a provider, with no ongoing commitment. This model suits people who rarely get sick or just want to test out a provider before committing to anything bigger.
Monthly or annual memberships charge a recurring fee in exchange for reduced-cost or unlimited visits. Families juggling multiple kids’ sniffles, or anyone who tends to need care several times a year, usually comes out ahead here. The math flips in your favor once you cross that number of visits per year, according to Zocdoc’s cost research.
Condition-specific subscriptions cover ongoing needs like weight management or mental health care. These typically bundle medication, lab work, or follow-up visits into one price, and because of that bundling they often run higher than a general membership, sometimes a substantial monthly amount, according to Telehealth Ally’s pricing analysis.
Employer or group plans are paid for (fully or partly) by your workplace. Coverage tiers and eligibility vary widely by employer, so what your coworker pays isn’t necessarily what you’ll pay. If you’re the one setting this up for a team, it helps to see how streamlined employee healthcare plans typically get structured before you commit to a vendor.
What Does Telehealth Cost Per Visit and Per Month?
Numbers help more than ranges alone, so here’s what you’re actually looking at when you open your wallet.
Per-visit self-pay pricing:
- Basic virtual urgent care (sore throat, rash, UTI): moderate cost range
- Primary care intake or a more involved evaluation: higher cost range
- Mental health therapy or psychiatry sessions: tends to be more expensive depending on provider and session length
Membership pricing:
- Basic plans with messaging and limited video visits: modest monthly fee
- Fuller plans with unlimited or near-unlimited primary care access: moderate monthly fee or an annual fee for some primary-care-focused plans, according to Zocdoc’s market survey
Pro Tip: Do the math on your own usage before you commit. Two visits a year at $75 each costs $150 in pay-per-visit fees. Six visits a year under a $20/month membership costs $240 annually, but if that membership includes visits that would otherwise run $75 each, you’d have paid $450 pay-per-visit for the same care.
One number worth sitting with: telehealth visits average $40 to $50 nationally, compared to roughly $136 for an in-person office visit. That gap alone explains a lot of the shift toward virtual care.
Keep in mind that prescriptions, lab work, imaging, and referrals to specialists are almost always billed separately from your visit fee or membership — see more details for patients on how lab/testing referral billing works at EIV Diagnostics. Budget for those extras, especially if your condition needs ongoing monitoring. For a deeper breakdown of what counts as an out-of-pocket expense versus what’s bundled, it helps to read the fine print before your first appointment.
Does Insurance or Medicare Cover Telehealth Visits?
Your coverage status changes this entire conversation, so let’s walk through what actually happens at checkout.
If you have Medicare Part B, you typically pay your annual deductible, then 20% coinsurance on the Medicare-approved amount for covered telehealth services, per Medicare. CMS has kept many pandemic-era telehealth flexibilities in place, with billing codes and originating-site rules that extend through 2026 under current CMS guidance, but you still need to confirm your specific provider bills correctly for Medicare to apply.
Commercial insurance usually treats telehealth like any other visit: an in-network copay if your plan includes the provider, or a higher out-of-network rate if it doesn’t. Some employers fold telehealth memberships directly into their group health benefits, which is worth checking with HR before you pay out of pocket.
Medicaid and federally funded health centers often provide low-cost or no-cost telehealth access for eligible patients. The HRSA health center locator can point you toward a sliding-scale clinic near you.
Before your first visit, take three steps:
- Call your insurer and ask specifically about telehealth cost-sharing.
- Check your plan documents or the Healthcare if you have a marketplace plan.
- Confirm with the provider how they bill, since HHS’s telehealth payment guidance notes that billing practices vary by platform.
How Do You Choose the Right Telehealth Pricing Plan?
Picking a plan comes down to being honest about how you actually use healthcare, not how you imagine you might use it.
Run through this checklist before signing up for anything:
- Estimate your annual visit count. Rare colds and one-off issues favor pay-per-visit; four or more expected visits favor membership.
- Identify your condition type. Chronic or ongoing issues almost always cost less under a subscription that bundles follow-ups.
- Factor in medication needs. Ask whether prescriptions are included or billed on top.
- Weigh access speed. Same-day availability matters more if you have kids or unpredictable symptoms.
- Clarify follow-up expectations. Some plans include check-ins; others charge per encounter every time.
Before paying anyone, ask these seven questions: What exactly is included in the price? Are medications billed separately? Do you cover lab or imaging referrals? Are your providers licensed in my state? What’s your cancellation and refund policy? How is my billing information protected? Will you clearly disclose any extra fees before I’m charged?
Watch for red flags like vague pricing pages, surprise referral charges, or providers who dodge questions about state licensing.
Worked example: a patient with seasonal allergies and one annual physical might spend $150 a year pay-per-visit. A parent managing two kids’ recurring ear infections and check-ups could spend $450+ pay-per-visit, versus $240 a year under a modest membership, according to Telehealth Ally’s cost comparisons.
How Chameleon Healthcare’s Membership Changes the Cost Equation
Chameleon Healthcare built its membership model around a simple frustration: patients rarely know what a visit will cost until the bill shows up. Chameleon Healthcare provides fast, affordable, accessible telehealth care without requiring insurance, which matters most for the uninsured patients who get hit hardest by opaque pricing elsewhere.
The membership structure combines urgent care and primary care access under one transparent price, with same-day availability that removes the guesswork of “will I get seen today.” That combination is what typically drives down hidden costs. You’re not paying a separate urgent care rate one week and a primary care rate the next.
When pricing is upfront and visits don’t carry surprise fees, patients make better decisions about when to seek care instead of delaying treatment out of cost anxiety. That’s the real value a transparent membership model provides.
Vector, who covers telehealth economics for the Chameleon Healthcare Blog, has tracked how membership structures affect real patient spending patterns across virtual healthcare models. The consistent finding: transparency at signup prevents most of the billing surprises patients report elsewhere.
How Long Do You Have to Commit to a Telehealth Membership?
Contract length varies more than most people expect, and it’s worth reading before you enter your card number.
Many consumer telehealth memberships run month-to-month, meaning you can cancel anytime without penalty. This is common for general primary care and urgent care memberships aimed at individuals and families. Others require an annual commitment, especially plans priced around that $99-a-year mark, since the lower per-month cost is the tradeoff for locking in for twelve months.
Condition-specific subscriptions, particularly for weight management or mental health, sometimes require a minimum commitment period, often three to six months, because treatment protocols need consistent follow-up to work properly. If you cancel early with these plans, you may lose access to bundled medication management mid-treatment, which can leave you scrambling for a new provider.
Employer-sponsored plans typically run on the employer’s benefits calendar, usually a full plan year, with enrollment windows that don’t always align with your personal preference for flexibility.
Before enrolling, ask directly: is this month-to-month, or am I locked in? What happens to my rate if I want to switch tiers mid-term? For most individuals and families, a flexible month-to-month structure is worth prioritizing unless the annual discount is substantial enough to offset the lost flexibility.
What Happens When You Cancel a Telehealth Membership?
Cancellation terms differ enough between providers that this deserves its own careful read before you sign up.
Reputable telehealth memberships let you cancel with a simple request through your account settings or by contacting customer support, usually without a penalty fee for month-to-month plans. Annual plans are trickier: canceling early sometimes means forfeiting the remaining prepaid months, though some providers offer prorated refunds if you ask.
A few things to watch for:
- Auto-renewal clauses. Many memberships renew automatically unless you cancel a set number of days before your billing cycle resets.
- Processing delays. Some platforms take a full billing cycle to process a cancellation, meaning you could be charged once more after requesting to leave.
- Data and prescription access. Ask what happens to your medical records and any active prescriptions once you cancel, especially with condition-specific subscriptions.
Legitimate providers disclose these terms clearly in their sign-up flow. If a platform buries its cancellation policy or makes it hard to find, that’s a signal worth taking seriously before you hand over payment information.
How Do Telehealth Membership Costs Compare Across Providers?
Pricing across the telehealth market clusters into recognizable bands rather than a single standard rate, which is exactly why comparing plans by category, not by brand alone, gives you a clearer picture.
General primary care and urgent care memberships mostly land in the $5 to $30 a month range, with annual plans often advertised around $99 a year for a full year of access. Mental health-focused platforms typically charge more per session, often $100 to $200+, because therapy and psychiatry involve longer appointments and specialized licensing. Condition-specific subscriptions, especially GLP-1 weight management programs, sit at the top of the range, frequently $99 to $299 or more a month, since the price includes medication management and regular check-ins.
Employer-sponsored plans are the hardest to compare directly since the employer absorbs part or all of the cost, and your personal price depends entirely on your benefits package. If you’re comparing your own out-of-pocket exposure against what a membership includes, a telehealth cost versus clinic breakdown makes the math easier to follow side by side.
The takeaway across categories: the lowest advertised price rarely tells the whole story. What’s bundled into that price, medication, labs, follow-ups, matters more than the sticker number alone.
When Membership Actually Pays Off
Membership makes the most financial sense for families with kids who catch everything going around, anyone managing a chronic condition that needs regular check-ins, and people who reach for urgent care more than a few times a year. If that’s not you, pay-per-visit usually wins, especially if you’re dealing with a single issue or still deciding whether a provider is the right fit. Either way, check your benefits first, add up a full year under both models, and if a provider offers a short trial period, use it before committing longer term.
— Vector
Chameleon Healthcare Plans: Where to See Real Pricing
If the math above has you leaning toward membership, the fastest way to see real numbers is to look at Chameleon Healthcare’s plans page, where pricing is listed upfront with no hidden tiers to decode. Membership includes unlimited or discounted virtual visits, same-day access when you need it, and one transparent price that covers urgent care and primary care together.
Signing up takes a few minutes, and you can choose monthly or annual billing depending on which fits your budget and expected usage. Employers exploring group enrollment can set up team access directly, with tiers built for small businesses that don’t want to navigate traditional group insurance. Whether you’re dealing with something specific, like a sprain that needs quick evaluation or ongoing heartburn management, membership gives you a same-day path to a licensed provider without a surprise bill waiting at the end. Visit the plans page to compare tiers and start your membership today.
This article is general information, not a substitute for advice from a qualified doctor. Consult a qualified healthcare professional about your own circumstances before acting on anything here.