
Two tax breaks do the heaviest lifting for small business owners and self-employed individuals when it comes to health costs. The Self-Employed Health Insurance deduction reduces your adjusted gross income (AGI) dollar for dollar, covering premiums you pay for medical, dental, vision, and qualifying long-term care coverage. The Small Business Health Care Tax Credit (Section 45R) cuts your actual tax bill, not just your income, by up to 50% of employer premium costs for taxable small employers or 35% for tax-exempt ones.
Beyond those two headline items, several other health-related costs are deductible as ordinary business expenses:
- Employer-paid premiums for employee health plans
- Employer contributions to Health Savings Accounts (HSAs)
- Reimbursements through Health Reimbursement Arrangements (HRAs), Qualified Small Employer HRAs (QSEHRAs), or Individual Coverage HRAs (ICHRAs)
- Employer-paid telehealth or subscription plan costs for employees
Employer HSA contributions are also exempt from payroll taxes, which adds a layer of savings beyond the income tax deduction. The main limits to know upfront: the Section 45R credit requires fewer than 25 full-time equivalent employees (FTEs) and average wages below the phaseout threshold; the self-employed deduction is capped at your net self-employment income and cannot be claimed for any month you had access to subsidized employer coverage, including through a spouse’s plan.
Pro Tip: If you are close to the FTE or wage phaseout thresholds for the Section 45R credit, run the numbers before year-end. A small change in how you count part-time hours or structure bonuses can shift your eligibility.
Key Takeaways
| Point | Details |
|---|---|
| Self-employed deduction | Above-the-line deduction on Schedule 1, capped at net self-employment income; covers medical, dental, vision, and qualifying long-term care premiums. |
| Section 45R credit | Worth up to 50% of premiums (35% for tax-exempt employers); requires fewer than 25 FTEs, wages below the phaseout threshold, ≥50% employer premium share, and SHOP enrollment. |
| Two-year credit window | The Small Business Health Care Tax Credit is available for two consecutive tax years only; plan which years give you the deepest eligibility. |
| HSA and QSEHRA options | 2026 HSA limits are $4,400 (self-only) and $8,750 (family); QSEHRA reimbursements are employer-deductible and employee tax-free but reduce Marketplace premium tax credits. |
| Chameleonhc employer plans | Employer-paid telehealth subscriptions are generally deductible as ordinary business expenses; review plan options at chameleonhc.com/plans and confirm treatment with your CPA. |
Table of Contents
- Who qualifies for small business tax health deductions?
- How to claim each deduction and where to report it
- How do HSAs, FSAs, HRAs, and QSEHRAs work for small employers?
- Worked examples: estimating your credit or deduction
- Recordkeeping you need and mistakes that cost you
- How Chameleonhc employer plans fit into U.S. small business tax rules
- What actually matters when choosing employer health options
- Chameleonhc employer plans: a practical next step for small businesses
- Sources
Who qualifies for small business tax health deductions?
Small Business Health Care Tax Credit eligibility
The Small Business Health Care Tax Credit has four hard requirements you must meet simultaneously:
- Fewer than 25 FTEs. Part-time employees count proportionally. Two half-time workers equal one FTE.
- Average annual wages below the phaseout threshold. The credit begins phasing out once average wages exceed the lower threshold and disappears entirely at the upper threshold.
- You pay at least 50% of enrolled full-time employees’ premium costs. This applies to the employee-only portion, not dependents.
- You offer coverage through the SHOP Marketplace. Buying coverage outside SHOP disqualifies you from the credit, even if every other condition is met.
The credit is available for two consecutive tax years, then it expires for that employer. As your FTE count or average wages rise toward the upper phaseout limits, the credit shrinks proportionally. An employer with 20 FTEs and wages near the upper threshold may receive only a fraction of the maximum credit, or none at all.
Self-employed health insurance deduction eligibility
You qualify if you have net self-employment income and you are not eligible for subsidized health coverage through an employer, including your spouse’s employer. The key word is eligible, not enrolled. If your spouse’s employer offered coverage and you declined it, you still cannot claim the deduction for those months.
S-corporation shareholders who own more than 2% of the company follow a separate path. The premium must be included in the shareholder-employee’s W-2 wages, and the deduction is then claimed on the shareholder’s personal Form 1040. The deduction in all cases is capped at your net self-employment earnings for the year, so a loss year can wipe out the deduction entirely. Tax treatment also varies by business structure for partnerships and C-corporations, making it worth confirming the right approach for your entity type.
How to claim each deduction and where to report it
Self-employed health insurance deduction
- Calculate your net self-employment income first. This is your ceiling.
- Add up premiums paid for medical, dental, vision, and qualifying long-term care coverage for yourself, your spouse, and dependents.
- If you have a complex situation (multiple plans, long-term care contracts, or S-corp ownership), use Form 7206 to compute the allowable deduction. Form 7206 replaced the older worksheet and is the IRS’s structured tool for these cases.
- Report the final deduction amount on Schedule 1 (Form 1040), Line 17.
- For S-corp owners, confirm the premium appears in Box 1 of your W-2 before claiming it on Schedule 1.
Detailed line-by-line guidance is available in the IRS Instructions for Form 7206, which also covers the long-term care insurance limits and S-corp shareholder rules.
Small Business Health Care Tax Credit
- Confirm SHOP enrollment for the coverage year you are claiming.
- Calculate your FTE count and average wages using IRS worksheets.
- Complete Form 8941 (Credit for Small Employer Health Insurance Premiums) and attach it to your business return.
- Pass the credit through to your personal return if you are a sole proprietor, partner, or S-corp shareholder.
- Remember the two-year consecutive limit. If you claimed the credit in 2024 and 2025, you cannot claim it again for 2026 under the same employer.
For employer-paid premiums, HSA contributions, and HRA/QSEHRA reimbursements, these flow through your business’s Schedule C, Form 1065, or Form 1120-S depending on entity type. Employer HSA contributions are reported on employees’ W-2s in Box 12 (Code W).
How do HSAs, FSAs, HRAs, and QSEHRAs work for small employers?
HSA basics
An HSA pairs with a High Deductible Health Plan (HDHP). Employer contributions are deductible as a business expense and excluded from employees’ taxable wages, including payroll taxes. For 2026, contribution limits are $4,400 for self-only coverage and $8,750 for family coverage, with a $1,000 catch-up for those 55 and older. These limits make HSAs one of the most tax-efficient tools available for reducing MAGI and protecting Marketplace subsidy eligibility.
FSAs, HRAs, QSEHRAs, and ICHRAs
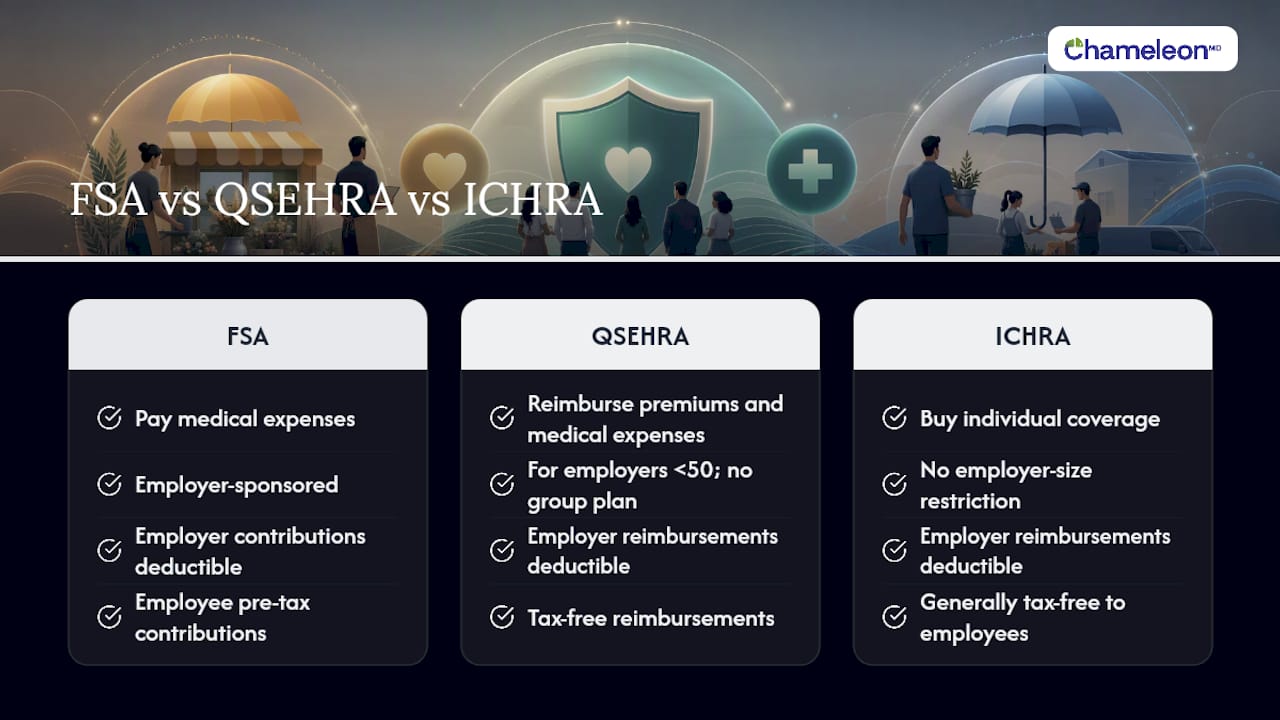
A Health FSA is employer-sponsored and lets employees set aside pre-tax dollars for medical expenses. Employer contributions are deductible; employee contributions reduce taxable wages.
A QSEHRA (Qualified Small Employer HRA) is designed specifically for employers with fewer than 50 full-time employees who do not offer a group health plan. You reimburse employees tax-free for individual premiums and qualified medical expenses up to annual IRS limits. The reimbursements are deductible to you as the employer. One important interaction: a QSEHRA reduces the employee’s Marketplace premium tax credit dollar for dollar, so employees receiving QSEHRA funds need to adjust their advance credit accordingly.
An ICHRA (Individual Coverage HRA) has no employer-size restriction and no annual cap. Employees use it to buy individual coverage. Like a QSEHRA, ICHRA reimbursements are deductible to the employer and generally tax-free to employees, but employees enrolled in an ICHRA are not eligible for Marketplace premium tax credits.
Telehealth and subscription plans
Employer-paid telehealth subscriptions are generally deductible as ordinary and necessary business expenses when provided as an employee benefit. You can offer a telehealth plan as a standalone benefit or integrate it within a QSEHRA structure, where the subscription cost counts toward the reimbursement cap. Employees receive the benefit tax-free, and you deduct the cost. See the employer healthcare access guide for a practical look at structuring these benefits.
Worked examples: estimating your credit or deduction
Example A: Very small employer, full credit
A bakery with 8 FTEs and average wages of $28,000 pays $24,000 in total annual premiums through SHOP and covers 100% of the employee-only premium. The employer meets all four credit conditions. The maximum credit is 50% of premiums paid, so the potential credit is $12,000. Because the FTE count and wages are well below the phaseout thresholds, the full credit applies.
Example B: Near the phaseout edge
A small consulting firm has 18 FTEs and average wages of $58,000. Both figures are inside the phaseout range. The credit percentage is reduced proportionally based on how far the FTE count and wages exceed the lower thresholds. After applying both phaseout reductions, the effective credit rate might drop to 10–15% of premiums rather than 50%, and a modest increase in headcount or a year-end bonus that raises average wages could push the credit to zero. Running the Form 8941 calculation before year-end lets you see exactly where you stand.
Example C: Self-employed filer with a premium tax credit
A freelance designer earns $52,000 in net self-employment income and pays $7,200 in annual premiums for a Marketplace plan. She also receives an advance premium tax credit (APTC) of $3,000. The self-employed health insurance deduction reduces her AGI, which in turn affects her final premium tax credit eligibility. Because the deduction and the credit depend on each other, the calculation is iterative: a larger deduction lowers AGI, which can increase the premium tax credit, which changes the net premium paid, which changes the deduction. Tax software handles this loop automatically. A CPA is worth consulting if your income is near a Marketplace subsidy cliff, since a small income change can shift the credit significantly.
Pro Tip: Use Form 7206 any time you have multiple health plans, long-term care premiums, or S-corp ownership. The structured worksheet prevents the most common calculation errors.
Recordkeeping you need and mistakes that cost you
Documentation checklist
- Payroll summaries showing hours worked, used to calculate FTE counts
- Proof of employer premium payments (invoices, canceled checks, bank statements)
- SHOP enrollment confirmation for any year you claim the Section 45R credit
- Form 7206 worksheets or the completed form itself
- W-2s for S-corp shareholders showing health premiums in Box 1
- Marketplace premium tax credit reconciliation (Form 8962) where applicable
- Written employer policy or plan document for any HRA, QSEHRA, or telehealth benefit
Common mistakes
- Claiming months with employer access. If you or your spouse had access to subsidized employer coverage at any point during the year, even if you declined it, those months are off-limits for the self-employed deduction. This is a frequent audit trigger.
- Miscounting FTEs or average wages. Part-time hours must be converted to FTE equivalents. Owners and family members are excluded from the FTE count for the Section 45R credit.
- Claiming the two-year credit a third time. The credit window is two consecutive tax years. Claiming it beyond that period is an error the IRS will catch.
- Missing the HSA employer contribution box. Employer HSA contributions belong in Box 12 (Code W) on the W-2. Omitting this creates a mismatch.
Pro Tip: Year-end retirement plan contributions (SEP-IRA, Solo 401(k)) reduce your MAGI and can shift your income below a Marketplace subsidy threshold, preserving premium tax credit eligibility. Run a quick projection in November or December before the window closes.
How Chameleonhc employer plans fit into U.S. small business tax rules
Employer-paid telehealth subscriptions, like the employer plans available through Chameleonhc, are generally treated as ordinary and necessary business expenses under IRS rules, making them deductible when you pay for employee coverage directly. The cost flows through your business return the same way a traditional group premium would, and employees receive the benefit tax-free.
These plans can be offered in a few ways. You can provide a telehealth subscription as a standalone employer benefit, which is straightforward to document and deduct. Alternatively, you can integrate the subscription cost within a QSEHRA structure, where it counts toward the annual reimbursement cap and employees use their QSEHRA funds to cover it. Either approach keeps the tax treatment clean, provided you maintain proper documentation.
For employees, receiving a telehealth benefit through their employer does not create taxable income when the arrangement qualifies as an employer-provided health benefit. If the benefit is offered through a QSEHRA, employees need to account for the reimbursement when reconciling their Marketplace premium tax credit on Form 8962. The cost comparison between telehealth and traditional clinic visits can also help you frame the value for employees.
When discussing Chameleonhc employer plans with your tax advisor, bring these documents:
- The plan documentation or service agreement showing it is an employer-paid benefit
- A written employer policy confirming the benefit is available to employees on a non-discriminatory basis
- Invoices or payment records showing the employer, not the employee, is paying
- Integration details if the plan is offered through a QSEHRA or HRA structure
What actually matters when choosing employer health options
The conventional wisdom says small employers should offer a group health plan or nothing at all. That framing misses a more practical middle ground that works well for very small firms.
For employers with fewer than 10 employees, a QSEHRA paired with a telehealth subscription often delivers better tax value per dollar spent than a full group plan. The QSEHRA keeps reimbursements deductible and tax-free, gives employees flexibility to choose their own coverage, and the telehealth subscription handles day-to-day care needs at a fraction of the cost of a traditional plan. The combination addresses the two things employees actually want: help paying for coverage and fast access to care when something comes up.
The two-year Section 45R credit window is worth thinking about strategically. If your FTE count or wages are trending upward, claiming the credit in the two years when you are most deeply inside the eligibility range makes more sense than waiting. Once you cross the phaseout thresholds, the credit is gone regardless of when you claim it.
The one situation where a CPA is genuinely necessary, not just helpful, is when your income sits near a Marketplace subsidy cliff. The iterative interaction between the self-employed health insurance deduction and the premium tax credit can produce meaningfully different outcomes depending on how the numbers fall, and tax software does not always surface the best path without some manual scenario testing.
Chameleonhc employer plans: a practical next step for small businesses
Offering employees access to quality care does not have to mean navigating expensive group insurance. Chameleonhc’s employer telehealth plans give your team same-day access to licensed providers for common conditions, with clear, upfront pricing and no waiting rooms. When you pay for employee coverage as the employer, the cost is generally deductible as an ordinary business expense, and your employees receive the benefit tax-free.
You can offer a Chameleonhc plan as a standalone employer benefit or integrate it within a QSEHRA structure to maximize tax efficiency. Either way, the documentation is straightforward: a service agreement, a written employer policy, and payment records showing the employer is covering the cost. Review the Chameleonhc virtual care and employer plans page to see current options, then bring the plan documentation to your CPA to confirm deductibility and how it interacts with any HRA or QSEHRA you already offer.
This article is general information, not tax or legal advice. Confirm your specific tax treatment with a qualified tax professional before making filing decisions.
Sources
- Small Business Health Care Tax Credit
- Small Business Health Options Program (SHOP) | CMS
- Is Health Insurance Tax Deductible for Small Businesses? - LegalClarity
- Beancount
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.