
The most common small business benefit gaps are medical/telehealth access, retirement savings plans, dental and vision coverage, disability and life insurance, paid leave, and mental health support. According to Urban Institute analysis, employees at firms with 50 or fewer workers face dramatically lower access to nearly every employer-sponsored benefit compared to those at larger companies. The fastest, lowest-cost first step for most small employers is adding a telehealth or virtual primary care plan, ideally paired with a voluntary benefits menu routed through a Section 125 cafeteria plan.
Here is a quick picture of where the gaps hit hardest:
- Medical access: Employees at micro/small firms have substantially lower access to employer-sponsored medical coverage compared to those at medium/large employers.
- Retirement: Access to defined contribution retirement plans is considerably lower for small-firm workers compared to those at larger firms.
- Dental and vision: Dental and vision care access rates are much lower among small-firm employees than among employees at larger firms.
- Disability insurance: Long-term disability coverage access is substantially lower for small-firm employees compared to those at larger companies.
- Life insurance: Life insurance access is significantly lower at small firms compared to larger employers.
- Mental health and wellbeing: Coverage is uneven across SMBs, with emotional support as the most common entry point but overall access inconsistent.
- Fertility and parental support: Sequoia’s 2026 SMB Benefits Benchmark finds that the majority of SMBs do not offer fertility coverage.
- Financial wellness: Perceived cost and lack of benefits expertise are the primary barriers keeping most small businesses from offering financial health programs.
The good news: you do not need to close every gap at once. A focused, phased approach, starting with the highest-impact, lowest-admin options, can meaningfully improve your offer within 60–90 days.
Key Takeaways
Small businesses face the widest benefit gaps in medical access, retirement, dental and vision, disability, and mental health, and closing even two or three of these gaps with low-cost options can meaningfully improve hiring, retention, and employee wellbeing.
| Point | Details |
|---|---|
| Medical access gap is largest | Only — of small-firm employees have employer-sponsored medical access, versus — at larger firms. |
| Telehealth is the fastest fix | A virtual primary care plan can be live in days and costs a fraction of a traditional group health plan. |
| Voluntary benefits cost employers little | Dental, vision, life, and disability can be offered as employee-paid voluntary benefits routed pre-tax through Section 125. |
| Survey employees before spending | A three-question anonymous survey prevents misallocating budget on benefits employees will not use. |
| Chameleonhc for employer medical access | Chameleonhc’s telehealth-first employer plans give small teams same-day virtual care with transparent, flat pricing. |
Table of Contents
- What does the data actually say about small business benefit gaps?
- Where do small businesses fall short, benefit by benefit?
- Why do these gaps persist at small businesses?
- How do benefit gaps affect hiring, retention, and productivity?
- What are the most practical solutions small businesses can adopt now?
- How do you decide which gaps to close first?
- Step-by-step implementation checklist
- What regulatory basics should small employers know?
- How Chameleon Healthcare’s employer plan closes the medical access gap
- How to use community resources and partnerships to fill benefit gaps
- How to assess what your employees actually need
- What do benefits actually cost, and how should you budget?
- An honest perspective on where small business benefits go wrong
- Chameleonhc’s employer health plans: built for small teams
- Sources
What does the data actually say about small business benefit gaps?
The numbers behind common small business benefit gaps are striking, and they come from two of the most authoritative sources available: the Bureau of Labor Statistics Employee Benefits Survey and the Urban Institute’s 2026 analysis. Together, they paint a consistent picture: the smaller the employer, the wider the gap.
The Urban Institute analysis, published in early 2026 using BLS survey data, compared access rates at micro/small employers (50 or fewer full-time equivalents) against medium/large employers (100 or more FTEs). The gaps are not marginal.
One important distinction the BLS data draws is between access and take-up. A benefit being offered does not mean employees enroll. Take-up rates at small firms tend to be lower still, partly because employee cost-share is higher and partly because communication around benefits is often minimal. That gap between what is offered and what employees actually use is one of the most underappreciated problems in small business HR.
The KFF 2024 Employer Health Benefits Survey adds important cost context: small employers pay significantly more per employee for health coverage than large employers, which compounds the access problem. When premiums are high and margins are thin, many owners simply stop offering coverage rather than find a lower-cost alternative.
Where do small businesses fall short, benefit by benefit?
Medical and telehealth access
Telehealth and virtual primary care plans offer a practical entry point, often at a fraction of traditional group plan costs, with same-day access and no waiting rooms. For employers who cannot yet afford a full group health plan, a telehealth membership for the team covers a wide range of everyday conditions and urgent needs.
Dental and vision
Both are well-suited to voluntary benefits: employees pay the premium themselves, but the employer gets group rates and the administrative simplicity of payroll deduction. Cost to the employer is often near zero, and perceived value to employees is high.
Retirement savings
SIMPLE IRAs and SIMPLE 401(k)s are specifically designed for employers with 100 or fewer employees, carry lower administrative overhead, and still allow meaningful employee contributions. The BLS data shows retirement access has been a persistent gap for small-firm workers across multiple survey cycles.
Disability and life insurance
Both are available as voluntary or employer-paid group products at relatively low cost. A basic group term life policy for a small team can cost less than $10 per employee per month. Short-term disability is often the more immediately valued product for employees with families.
Paid leave
Paid leave policies at small firms vary widely. Many owners offer informal arrangements rather than a documented policy, which creates inconsistency and legal exposure. A written paid time off (PTO) policy costs nothing to implement and signals stability to candidates. Where state paid family and medical leave programs exist, enrolling employees is often straightforward and low-cost.
Mental health and wellbeing
Coverage is uneven. An Employee Assistance Program (EAP) is the most accessible entry point: most EAPs cost $1–$5 per employee per month and provide confidential counseling referrals, financial coaching, and crisis support. Sequoia’s 2026 benchmark confirms that emotional support is the most common wellbeing entry point for SMBs, but overall coverage remains inconsistent.
Fertility and parental support
Sequoia’s data is clear: 77% of SMBs offer no fertility coverage. For most small employers, this gap is not closable with a traditional fertility benefit right away. A practical first step is adding a parental leave policy and ensuring the EAP covers family-forming counseling.
Financial wellness and student-loan support
The FinHealth Network research identifies perceived cost and lack of expertise as the two biggest barriers keeping small businesses from offering financial health benefits. Basic financial planning access and payroll-integrated student-loan repayment support are available as voluntary add-ons through several benefits platforms, often at low or no direct employer cost.
Pro Tip: Before investing in any new benefit, send a two-question pulse survey to your team: “Which benefit would most improve your day-to-day life?” and “Would you contribute to this benefit if the employer covered part of the cost?” The answers will tell you exactly where to spend your first dollar.
Why do these gaps persist at small businesses?
Understanding the structural causes helps you address them more realistically, rather than treating every gap as a simple failure of will or budget.
- Higher per-employee costs. Small employers lack the negotiating leverage of large groups. Health premiums per employee can run 18–24% higher, and administrative fees for plan management are spread across fewer people, making the per-head cost of any benefit significantly steeper.
- Limited administrative capacity. A 15-person company rarely has a dedicated HR team. Benefits administration, compliance tracking, and open enrollment communication often fall to an owner or office manager who is already stretched. Complex plans with multiple vendors, eligibility rules, and reporting requirements simply do not get implemented.
- Workforce composition. Part-time and seasonal workers lower the average hours worked per employee, which affects mandate applicability and enrollment likelihood. When a significant portion of your workforce works fewer than 30 hours per week, ACA coverage mandates may not apply, and those employees may not prioritize or be eligible for employer-sponsored benefits.
- Regulatory thresholds and compliance burden. The ACA employer mandate applies to employers with 50 or more full-time equivalent employees. Firms just below that threshold often avoid expanding headcount or benefits to stay under it. ERISA plan document requirements, COBRA administration, and state leave program compliance all add layers that feel disproportionate for a small team.
- Awareness gaps. Many small business owners are not aware of lower-cost alternatives like SIMPLE IRAs, voluntary benefits routed through Section 125 plans, or association health plans. The complexity of the benefits market itself is a barrier.
How do benefit gaps affect hiring, retention, and productivity?
The business cost of leaving these gaps open is not abstract. When candidates compare offers, benefits are a primary decision factor, and a missing retirement plan or no health coverage can cost you the hire. Workplace Fairness notes that unfulfilled benefit promises are a significant driver of employee distrust and turnover, particularly when employees feel misled about what was offered during hiring.
- Turnover costs are real. Replacing an employee typically costs a meaningful share of their annual salary in recruiting, onboarding, and lost productivity. For a small team, even one or two departures per year can strain operations and budget.
- Offer acceptance rates drop. Candidates who receive competing offers with stronger benefits packages often decline positions at small firms, even when base pay is comparable. The business case for offering healthcare benefits is well-documented: employees rank health coverage among the top two or three factors in job decisions.
- Financial insecurity reduces productivity. Employees without retirement savings or emergency financial support are more likely to experience stress that affects focus and attendance. An EAP or basic financial wellness program addresses this at low cost.
- Absenteeism increases when healthcare access is limited. When employees cannot afford or access primary care, minor conditions become serious ones. Untreated illness leads to longer absences. A telehealth plan for small businesses directly reduces this pattern by making care fast and affordable.
What are the most practical solutions small businesses can adopt now?
Ranked by speed of implementation and employer effort required:
-
Telehealth or virtual primary care plan (Implementation: days to 2 weeks | Cost: low). This is the fastest, most visible fix for the medical access gap. Employees get same-day access to licensed providers for common conditions without insurance. Employer cost is typically a flat monthly fee per employee. Chameleonhc’s employer plans are built specifically for this use case.
-
Voluntary benefits with Section 125 routing (Implementation: 2–6 weeks | Cost: low to employer). Dental, vision, life, and disability coverage can all be offered as voluntary products where employees pay the premium. Routing premiums through a Section 125 cafeteria plan reduces employee taxable income and lowers the employer’s FICA liability. The payroll integration is the main setup step.
-
SIMPLE IRA or SIMPLE 401(k) (Implementation: 4–8 weeks | Cost: low to medium). Designed for employers with 100 or fewer employees, these plans require a mandatory employer contribution (either a match or a non-elective contribution) but carry far lower administrative overhead than a traditional 401(k). Several payroll platforms now offer integrated SIMPLE IRA setup.
-
Employee Assistance Program (EAP) (Implementation: 1–2 weeks | Cost: low, typically $1–$5 per employee per month). An EAP covers mental health counseling referrals, financial coaching, legal consultation, and crisis support. It is one of the highest perceived-value benefits per dollar spent and requires almost no ongoing administration.
-
HSA with payroll pre-tax routing (Implementation: 3–6 weeks | Cost: low to medium). If you offer a high-deductible health plan (HDHP), pairing it with a Health Savings Account lets employees save pre-tax dollars for medical expenses. Employer contributions to the HSA are also tax-advantaged.
-
Pooled purchasing or association health plans (Implementation: 4–12 weeks | Cost: medium). Joining a trade association or professional employer organization (PEO) can give small employers access to group health rates that would otherwise be unavailable. This is a longer-term play but can meaningfully reduce per-employee premium costs.
Pro Tip: Combine voluntary dental and vision with Section 125 routing from day one. The employer cost is near zero, the tax savings are real for both parties, and employees see two new benefits on their pay stub immediately. It is the highest perceived-value-per-dollar move most small employers have not made yet.
Pro Tip: Pilot telehealth for 60 days before committing to a full group health plan. Track utilization, gather employee feedback, and use that data to justify the cost to leadership or to decide whether a full plan is even necessary for your workforce’s needs.
How do you decide which gaps to close first?
A simple decision framework helps you rank options before spending a dollar. Score each potential benefit on four dimensions:
- Employee demand (high/medium/low): What does your team actually want? Survey results should drive this score.
- Legal or mandate urgency (required/recommended/optional): ACA obligations, state leave programs, and ERISA requirements come first.
- Cost to employer (low/medium/high): Factor in both premium cost and administrative time.
- Expected uptake (high/medium/low): A benefit no one uses wastes budget and goodwill.
Sample budget rules by firm size
At 50 employees, you are approaching ACA mandate territory and should budget for a compliant health offering as a baseline, with voluntary benefits layered on top.
A quick survey prompt to gauge employee priorities before you commit:
“We are reviewing our benefits package. Please rank the following in order of importance to you: health coverage, dental/vision, retirement savings, paid leave, mental health support, financial planning assistance. Any comments on what would most improve your experience here?”
That single survey, sent before your next benefits decision, can save you from spending on the wrong gap first.
Step-by-step implementation checklist
30-day actions
- Conduct employee needs survey (see prompt above).
- Audit current benefits: document what is offered, what employees actually use, and what is missing.
- Identify legal obligations: confirm your FTE count relative to ACA (50 FTE threshold), FMLA (50 employees within 75 miles), and any applicable state leave programs.
- Request quotes from at least two telehealth providers and one voluntary benefits broker.
- Confirm payroll system’s Section 125 and HSA integration capabilities.
60-day actions
- Select and contract with chosen vendors (telehealth, EAP, voluntary benefits).
- Set up Section 125 plan document if not already in place (requires a formal written plan).
- Draft a one-page benefits summary for employees covering what is new, what it costs them, and how to enroll.
- Schedule a 30-minute all-hands or team meeting to walk through changes.
- Send enrollment instructions with a clear deadline.
90-day actions
- Confirm enrollment numbers and follow up with non-enrollees.
- Track early utilization data (telehealth visits, EAP calls, voluntary plan enrollments).
- Set a 12-month review date to measure uptake, employee satisfaction, and any retention signals.
- Identify the next gap to address based on survey feedback and utilization data.
Questions to ask vendors and brokers
- What is the all-in cost per employee, including administrative fees?
- How does the employee cost-share affect take-home pay, and can premiums be routed pre-tax?
- Does your platform integrate with our payroll system, and what does that setup require?
- Do you support Section 125 plan administration, or do we need a separate TPA?
- What data and utilization reports do you provide, and how often?
- How is employee data protected, and what are your HIPAA compliance certifications?
- What is your enrollment support process: do you provide employee-facing materials?
Communication plan basics: Send a benefits announcement email, include a one-page summary in the onboarding packet for new hires, and schedule a quarterly reminder about underused benefits (EAP utilization, for example, is notoriously low when employees forget it exists). For enrolling employees in virtual care, a short how-to video or step-by-step PDF dramatically increases first-use rates.
What regulatory basics should small employers know?
This section is a general overview, not legal advice. Consult employment counsel before making changes that affect plan structure or employee eligibility.
- ACA employer mandate: Applies to employers with 50 or more full-time equivalent employees (Applicable Large Employers, or ALEs). If you are below 50 FTEs, you are not required to offer health coverage under the ACA, but state laws may impose additional requirements. Crossing the 50-FTE threshold triggers significant compliance obligations.
- COBRA: Federal COBRA continuation coverage applies to employers with 20 or more employees. Employees who lose coverage due to qualifying events (termination, reduction in hours) must be offered the option to continue coverage at their own expense. Firms with fewer than 20 employees may be subject to state mini-COBRA laws, which vary by state.
- ERISA: The Employee Retirement Income Security Act governs most employer-sponsored retirement and welfare benefit plans. Even small employers offering a group health plan or retirement plan must maintain a written plan document, a summary plan description (SPD) for employees, and meet basic fiduciary standards. ERISA compliance is not optional once a plan exists.
- FMLA: The Family and Medical Leave Act applies to employers with 50 or more employees within 75 miles of a worksite. Employees must have worked at least 12 months and 1,250 hours to be eligible. Many states have their own paid family and medical leave programs with different thresholds, some covering employers with as few as one employee.
- State leave programs: California, New York, New Jersey, Washington, Massachusetts, Connecticut, Oregon, Colorado, and several other states have mandatory paid leave programs. Check your state’s Department of Labor website for current thresholds and contribution requirements.
How Chameleon Healthcare’s employer plan closes the medical access gap
The medical access gap is the largest and most consequential gap small businesses face, and it is the one Chameleonhc is built to address directly. Here is how a typical employer pilot works in practice.
A small employer with 20 employees adds Chameleonhc’s telehealth-first employer plan. Employees receive same-day access to licensed providers for urgent care and primary care needs, including common conditions like sore throats, sinus infections, rashes, and more, all from their phone or computer. No waiting rooms. No insurance required. Transparent pricing from the start.
What the employer gets:
- A flat, predictable monthly cost per employee with no surprise billing.
- Coverage for a wide range of everyday conditions, reducing the need for expensive urgent care clinic visits.
- Simple enrollment: employees sign up in minutes, and the plan does not require complex payroll integration to launch.
- Primary care and urgent care scope in one plan, so employees are not bouncing between providers for routine needs.
- Options to scale: individual memberships, family coverage, or team-wide plans depending on your headcount and budget.
What employees experience:
- A same-day appointment for a health concern, without taking half a day off work.
- Clear, upfront pricing so there are no billing surprises.
- Care accessible from home, the office, or anywhere with a phone signal.
Pro Tip: Position the telehealth plan to employees as “your first call for any health question,” not just for emergencies. Teams that use it for routine check-ins and prescription refills get the most value and report the highest satisfaction.
For employers who want to see how virtual care ROI plays out in practice, real-world case examples show faster access, lower per-visit costs, and measurably higher employee satisfaction compared to leaving the medical gap open.
How to use community resources and partnerships to fill benefit gaps
Not every benefit gap requires a commercial product. Several low-cost or no-cost resources are available to small employers willing to look beyond the standard broker menu.
Trade associations and chambers of commerce often offer group health or dental plans to members at negotiated rates. If you belong to an industry association, check whether it offers a group benefits program. The savings on per-employee premiums can be significant compared to going to market alone.
State and local small business development centers (SBDCs) provide free consulting on benefits options, including guidance on which state programs your employees may qualify for independently (Medicaid, CHIP for dependents, state marketplace plans). Helping employees access individual coverage they qualify for on their own reduces the pressure on your employer plan budget.
Community mental health centers and nonprofit EAP providers offer sliding-scale or subsidized counseling services that can supplement or replace a commercial EAP for very small teams. Some United Way chapters and community foundations fund employee assistance resources specifically for small business employees.
Payroll and HR platforms like Gusto, Rippling, or Justworks bundle benefits access, Section 125 administration, and compliance support into a single monthly fee. For a small employer without a dedicated HR person, this kind of platform can make benefits administration genuinely manageable.
Professional employer organizations (PEOs) co-employ your workforce and pool employees across many small businesses to access large-group benefit rates. The National Association of Professional Employer Organizations (NAPEO) maintains a directory of certified PEOs. This is a medium-term solution, not a quick fix, but it can close multiple gaps simultaneously.
How to assess what your employees actually need
A benefits package built on assumptions is a benefits package that underperforms. The most reliable way to identify employee benefit gaps is to ask directly, and to ask in a way that gives you usable data.
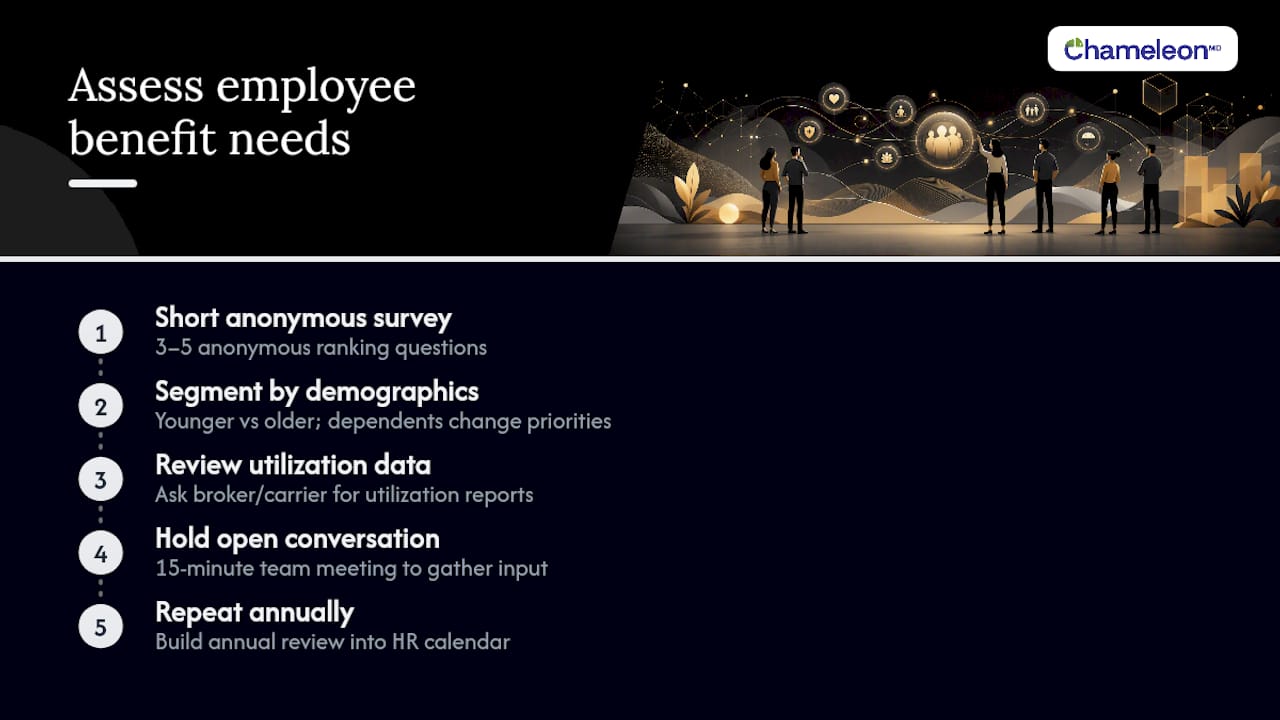
Start with a short anonymous survey. Three to five questions are enough. Ask employees to rank benefit categories by personal importance, indicate whether they would contribute to a voluntary benefit if offered, and flag any current health or financial needs that are going unmet. Anonymous responses tend to be more honest, especially in small teams where employees worry about being identified.
Segment by workforce demographics. A team of 25-year-olds has different priorities than a team of 40-year-olds with families. If your workforce skews younger, student-loan repayment support and mental health access may rank higher than life insurance. If you have more employees with dependents, dental and vision for families and parental leave policies will matter more.
Review claims and utilization data if you already have a plan. If you offer any existing benefits, your broker or carrier can provide utilization reports. Low utilization on a benefit you are paying for is a signal to either communicate it better or redirect that budget to something employees will actually use.
Hold a brief open conversation. A 15-minute team meeting where you say “We are reviewing our benefits and want your input” builds trust and often surfaces specific needs that a survey would miss. Employees who feel heard are more likely to enroll and engage with whatever you add.
Repeat the assessment annually. Workforce demographics and priorities shift. A benefits package that was right for your team two years ago may be missing the mark today. Building a simple annual review into your HR calendar keeps your offering aligned with actual employee needs.
What do benefits actually cost, and how should you budget?
Cost ranges vary by benefit type, vendor, and workforce size, but the following gives you a working framework for small business benefits analysis.
Medical/telehealth: A traditional group health plan for a small employer can run $500–$800 or more per employee per month in total premium (employer plus employee share), based on KFF survey data. A telehealth-first plan or virtual primary care membership typically costs a fraction of that, often in the range of $20–$50 per employee per month for employer-sponsored access, making it the most accessible entry point for employers who cannot yet afford a full group plan.
Dental and vision (voluntary): When offered as voluntary benefits with employee-paid premiums, the direct cost to the employer is often near zero beyond the administrative setup. Group rates through a broker typically run $15–$40 per employee per month for dental and $5–$15 for vision, paid by the employee through payroll deduction.
EAP: Typically $1–$5 per employee per month. For a 25-person team, annual cost is $300–$1,500. Few benefits deliver this much perceived value per dollar.
Life and disability (voluntary or employer-paid): Basic group term life can cost $5–$15 per employee per month for employer-paid coverage. Short-term disability group rates vary by benefit level and waiting period but are often available in the $10–$30 per employee per month range.
For a 20-person team with average annual salaries of $50,000 (total payroll $1,000,000), that is $30,000–$60,000 per year, or $1,500–$3,000 per employee. Prioritizing telehealth, an EAP, and voluntary dental/vision gets you meaningful coverage across the most visible gaps within that range.
An honest perspective on where small business benefits go wrong
The data on identifying employee benefit gaps is clear, and the solutions are more accessible than most small business owners realize. What actually holds employers back is not cost alone. It is the habit of treating benefits as a one-time administrative task rather than an ongoing part of compensation strategy.
The employers who close gaps most effectively are the ones who survey their teams before spending, pilot one or two high-impact options first, and then communicate those benefits repeatedly throughout the year. An EAP that employees forget about is an EAP that does not reduce absenteeism or improve retention. A telehealth plan that sits unused because no one explained how to log in is a wasted line item. The implementation is only half the job. The other half is making sure employees actually use what you have built for them.
Treat your benefits package the way you treat your product: launch, measure, iterate. The first year is a pilot. The second year is where you optimize.
Chameleonhc’s employer health plans: built for small teams
Closing the medical access gap does not have to mean navigating a complex group health plan with months of setup and unpredictable costs. Chameleonhc offers telehealth-first employer health plans designed specifically for small businesses: same-day virtual visits, primary and urgent care in one plan, transparent pricing, and no insurance required.
For a small team, the math is straightforward. A flat monthly cost per employee, no surprise billing, and care that employees can actually access from their phone on a Tuesday morning. Conditions covered include everything from sore throats and sinus infections to rashes, heartburn, and more. You can explore the full scope of conditions covered through telehealth to see how it maps to your team’s everyday needs.
If you are ready to close the medical access gap for your team, visit Chameleonhc to request pricing or start a pilot for your small business today.
Sources
The figures and analysis in this guide draw from the following primary sources. Each is worth consulting directly if you want to go deeper on a specific gap or verify the numbers for your own planning.
- Exploring the Small Business Employee Benefits Gap
- Employee Benefits in the United States — BLS news release (EBS tables)
- 2026 SMB Benefits Benchmark Insights
- 2024 Employer Health Benefits Survey — KFF
- Boosting Financial Health Benefits in the Small Business Workplace (FinHealth Network, 2023)