
If you’re trying to figure out how to get affordable medical care, the U.S. safety net has more options than most people realize. The main types of income-based care programs fall into five categories: federal and state public insurance (Medicaid and CHIP), Marketplace subsidies through HealthCare.gov, hospital financial assistance policies (also called charity care or FAPs), community-based sliding-fee clinics (FQHCs, RHCs, and free clinics), and targeted federal programs like Ryan White and Hill-Burton. Each works differently, covers different people, and asks for different documentation.
Here’s a quick map of where to start based on your situation:
- Low income, no insurance: Check Medicaid eligibility first at Medicaid.gov or your state’s Medicaid office. If you don’t qualify, look for a Federally Qualified Health Center (FQHC) near you using the HRSA Find a Health Center tool.
- Facing a hospital bill you can’t pay: Ask the billing office for the hospital’s Financial Assistance Policy (FAP) application. Nonprofit hospitals are legally required to have one under Section 501® of the tax code.
- Need care now, income too high for Medicaid: A Marketplace plan with premium tax credits may cut your monthly cost significantly, or a community free clinic can see you while you sort out coverage.
- Living with HIV, a chronic condition, or a specific diagnosis: Programs like Ryan White or Section 340B drug discounts may cover care and prescriptions at little or no cost.
- Need a same-day visit for a common condition: Affordable telehealth options like Chameleonhc offer transparent pricing and no waiting rooms, which can be a practical option while you work through program eligibility.
Table of Contents
- What counts as an income-based care program?
- How do Medicaid and CHIP work, and who qualifies?
- What does hospital financial assistance (charity care) actually cover?
- How do community clinics and sliding-fee programs work?
- What are Ryan White, Hill-Burton, 340B, and other targeted programs?
- How do you find and apply for income-based care programs?
- How much does hospital charity care vary, and why does it matter?
- Key Takeaways
- Why program literacy changes outcomes for low-income patients
- Telehealth as an affordable option when public programs aren’t yet in place
- Authoritative resources for enrollment and program information
What counts as an income-based care program?
The phrase “income-based care program” covers any arrangement where your household income determines whether you qualify, how much you pay, or both. That sounds simple, but the underlying eligibility logic varies a lot across program types, and mixing them up can lead to missed benefits or wasted time.
The five main categories differ in who runs them, how they calculate income, and what they actually cover:
| Program Type | Who Is Covered | How Income Is Counted | Services Covered | Cost to Patient | How to Apply |
|---|---|---|---|---|---|
| Medicaid / CHIP | Low-income adults, children, pregnant individuals, people with disabilities | Modified Adjusted Gross Income (MAGI) for most groups; asset tests for some elderly/disabled | Broad: primary, specialty, hospital, prescriptions, mental health | Free or very low copays | HealthCare.gov, state Medicaid office, or in person |
| Marketplace (ACA subsidies) | Individuals/families not eligible for Medicaid, with income 100%–400%+ FPL | MAGI-based household income | Varies by plan; essential health benefits required | Reduced premiums; cost-sharing reductions on silver plans | HealthCare.gov during open enrollment or special enrollment |
| Hospital FAP / Charity Care | Uninsured or underinsured patients at nonprofit hospitals | Hospital-set income cutoffs vary widely, often including asset review | Hospital services (inpatient, outpatient, ER) | Free or discounted, capped at Amounts Generally Billed (AGB) | Apply directly to hospital billing office |
| FQHCs / Free Clinics / RHCs | Anyone, regardless of insurance or immigration status | Sliding-fee scale based on income and family size | Primary care, dental, behavioral health, pharmacy (varies) | Sliding scale; some services free | Walk in or call; bring ID and income documentation |
| Targeted Federal Programs (Ryan White, Hill-Burton, 340B) | Condition-specific or facility-specific populations | Program-specific rules; often income-verified | HIV care, hospital services, prescription drugs | Free or deeply discounted | Through program-specific enrollment or HRSA-linked sites |
Understanding which category fits your situation is the first step. The sections below go deeper on each one.
How do Medicaid and CHIP work, and who qualifies?
Medicaid and CHIP together cover low-income adults, children, pregnant individuals, older adults, and people with disabilities. CHIP specifically fills the gap for children whose family income is too high for Medicaid but still too low to afford private coverage comfortably.
Who typically qualifies
In states that expanded Medicaid under the Affordable Care Act, most adults with household incomes up to roughly 138% of the Federal Poverty Level (FPL) qualify. In non-expansion states, eligibility is much narrower and often limited to parents of dependent children, pregnant individuals, and people with qualifying disabilities. Children generally qualify at higher income thresholds than adults, and pregnant individuals often qualify at higher limits than other adults in the same state.
How income is counted: MAGI basics
Most Medicaid and CHIP eligibility decisions use Modified Adjusted Gross Income (MAGI). MAGI starts with your adjusted gross income from your tax return and adds back certain deductions like non-taxable Social Security benefits and tax-exempt interest. Household size matters just as much as the dollar amount, because the FPL thresholds scale with family composition. A single adult at 138% FPL faces a different dollar cutoff than a family of four at the same percentage.
One thing that trips people up: MAGI rules apply to most non-elderly, non-disabled adults, but older adults and people with disabilities applying for certain Medicaid categories may still face asset tests. If you own a home, a car, or have savings, those rules can affect eligibility in ways that MAGI alone doesn’t capture.
State variation and common pitfalls
States administer Medicaid within federal guidelines, so benefits, income cutoffs, and even the name of the program differ. Some states have waiting periods for CHIP. Others have residency requirements that can complicate eligibility for people who recently moved. If you’re in a non-expansion state and your income falls below 100% FPL, you may fall into a “coverage gap” where you don’t qualify for Medicaid but also can’t get Marketplace subsidies.
How to apply
- Go to HealthCare.gov or your state’s Medicaid portal and complete a screening.
- Gather documents: photo ID, Social Security numbers for household members, recent pay stubs or a tax return, and proof of residency.
- Submit the application online, by phone, or in person at your local Medicaid office.
- If approved, coverage can sometimes be backdated to the month you applied or even earlier in some states.
- If denied, you have the right to appeal. Request a fair hearing through your state agency.
Pro Tip: Estimate your MAGI before you apply by adding up your gross wages, self-employment income, and any taxable benefits, then check where that total falls relative to your state’s FPL cutoff. If your income is close to the line, ask a certified application assister (available free through many FQHCs and community organizations) to help you document your household correctly before submitting.
Research on financial assistance programs confirms that fragmented program structures and varied eligibility rules are among the biggest barriers to enrollment, making navigator support genuinely useful rather than just a nice extra.
What does hospital financial assistance (charity care) actually cover?
When a nonprofit hospital treats you and you can’t afford the bill, the hospital’s Financial Assistance Policy (FAP) is your legal right to ask about. Under Section 501® of the Internal Revenue Code, every nonprofit hospital must maintain a written FAP that describes who qualifies, what assistance is available, and how the hospital determines what it will charge eligible patients.
What the law requires
The FAP must spell out eligibility criteria, the types of assistance offered (free care, discounted care, or both), and the method used to calculate the Amounts Generally Billed (AGB). The AGB is the ceiling on what a hospital can charge a FAP-eligible patient. Charging more than AGB to someone who qualifies for financial assistance is a violation of federal tax rules. The hospital must also have an emergency medical care policy consistent with EMTALA, meaning it cannot deny emergency stabilization based on your ability to pay.
Why eligibility varies so much
Here’s where things get complicated. While the law sets the framework, hospitals set their own income cutoffs and asset rules within that framework. Research published in Health Affairs found that income limits for free care at nonprofit hospitals ranged from 41% to 600% of the Federal Poverty Level, with a median free-care cutoff around 200% FPL and a median discounted-care cutoff around 400% FPL. Many hospitals also conduct asset reviews, meaning savings accounts, home equity, or other assets can affect your eligibility even if your income qualifies.
That range is wide enough to mean that two patients with identical incomes, treated at two different hospitals in the same city, could face very different financial outcomes.
What to do at the billing office
- Ask specifically for the FAP application, not just a “payment plan.”
- Request a written explanation of how the hospital calculates AGB and what your maximum charge would be if you qualify.
- Bring pay stubs, your most recent tax return, and a bank statement if the hospital conducts asset reviews.
- If you’re denied, ask for the appeals process in writing. Many hospitals have a charity review board.
- File your FAP application promptly. Some hospitals set deadlines (often 240 days from the first billing statement) after which they may send accounts to collections.
Pro Tip: Keep a written record of every conversation with the billing office, including the date, the name of the person you spoke with, and what was said. If your account goes to collections before your FAP is processed, that documentation can support a dispute under the Fair Debt Collection Practices Act.
How do community clinics and sliding-fee programs work?
Community-based clinics are designed to fill the gaps that insurance programs leave open. They serve patients regardless of ability to pay, immigration status, or insurance coverage, and they adjust what you owe based on your income and family size.
The main types of community clinics
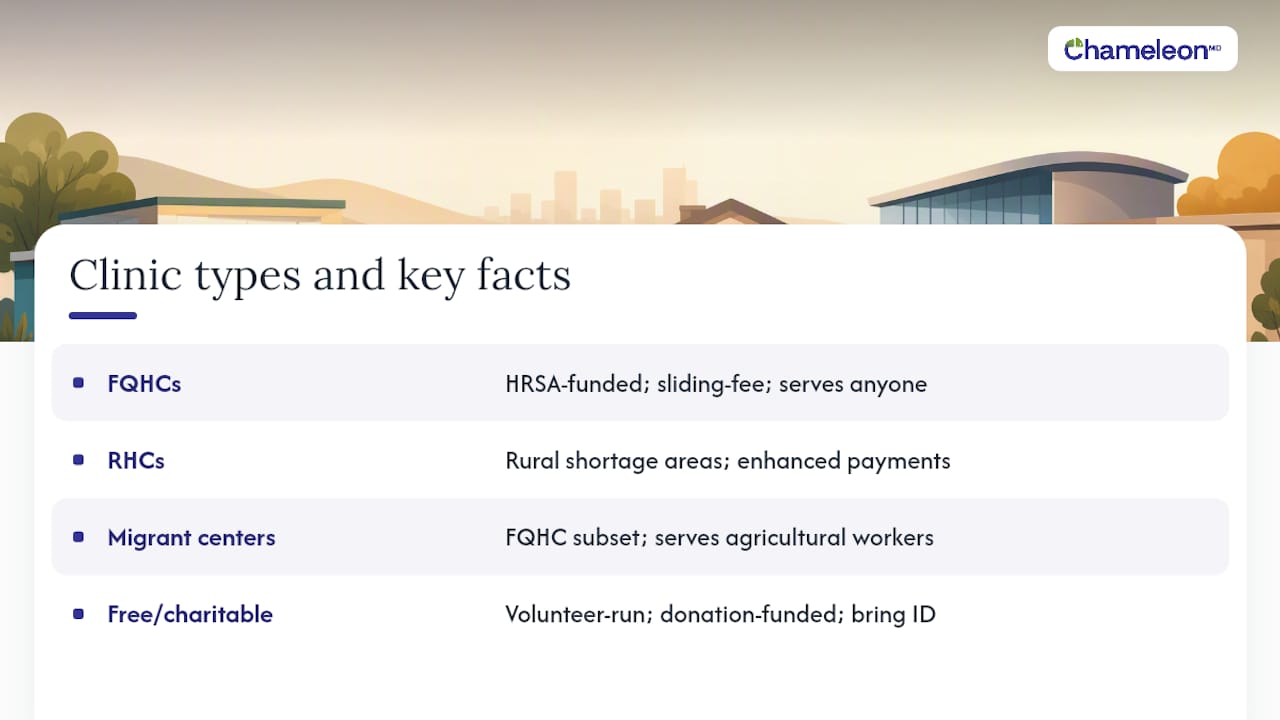
Federally Qualified Health Centers (FQHCs) receive federal funding through HRSA and are required by law to offer services on a sliding-fee scale. They provide primary care, dental, behavioral health, and often pharmacy services. FQHCs must serve anyone who walks in, which makes them one of the most reliable options for uninsured patients. You can find one near you using the HRSA Find a Health Center tool at findahealthcenter.hrsa.gov.
Rural Health Clinics (RHCs) operate in designated rural shortage areas and receive enhanced Medicare and Medicaid reimbursements. They’re not required to offer sliding-fee scales in the same way FQHCs are, but many do, and they’re often the only primary care option in their communities.
Migrant health centers are a subset of FQHCs specifically funded to serve agricultural workers and their families. They often have staff who speak Spanish and other languages and are familiar with the documentation challenges migrant workers face.
Free and charitable clinics operate outside the federal grant system entirely, relying on volunteer providers and donations. The National Association of Free & Charitable Clinics (NAFC) maintains a directory of these clinics and advises patients to bring a photo ID, a current medication list, and any available medical records to speed up intake.
What sliding-fee scales actually mean for your bill
A sliding-fee scale ties your out-of-pocket cost to your income as a percentage of the FPL. At the lowest income levels, care may be entirely free. At moderate incomes, you might pay a nominal fee per visit, often in the range of a few dollars to around $40, depending on the clinic and the service. Specialty care is less commonly available at FQHCs, so complex conditions may still require a referral to a hospital or specialist, where different cost rules apply.
For behavioral health specifically, sliding-scale therapy follows a similar model and can make mental health services accessible at community clinics and affiliated practices.
- Bring photo ID and proof of income (pay stubs, a tax return, or a benefits letter).
- If you have no documentation, many clinics will still see you and use a self-attestation process.
- Ask about pharmacy services at the first visit. Many FQHCs participate in the 340B drug pricing program, which can significantly reduce prescription costs.
- Dental and behavioral health services are available at many FQHCs but may have separate wait lists.
What are Ryan White, Hill-Burton, 340B, and other targeted programs?
Beyond the broad safety-net programs, several targeted federal programs provide financial support for health services to specific populations. These often work alongside Medicaid or FQHC care rather than replacing it.
-
Ryan White HIV/AIDS Program: Funded by HRSA, this program provides care and support services for people living with HIV who have no other means to pay. It covers medical visits, medications (including antiretrovirals), case management, and some support services. Eligibility is income-based and verified through local Ryan White grantees. Find your local program through the HRSA Ryan White HIV/AIDS Program directory.
-
Hill-Burton Free and Reduced-Cost Health Care: Hospitals and clinics that received federal construction funds under the Hill-Burton Act are obligated to provide a certain amount of free or reduced-cost care. The program is administered by HRSA, and the list of participating facilities is available at hrsa.gov. Eligibility is income-based, and the program covers services at the specific facility that received the funding.
-
Section 340B Drug Pricing Program: This federal program requires pharmaceutical manufacturers to sell outpatient drugs to eligible health care organizations at significantly reduced prices. Patients treated at 340B-covered entities (including many FQHCs and Ryan White grantees) benefit from lower drug costs, though the savings structure varies by facility. You don’t apply for 340B directly; you benefit from it automatically when you receive care at a participating site.
-
Prescription assistance programs: Most major pharmaceutical manufacturers operate patient assistance programs (PAPs) for people who can’t afford their medications. NeedyMeds and RxAssist maintain searchable databases of these programs. Income thresholds and application processes vary by manufacturer and drug.
-
State pharmaceutical assistance programs (SPAPs): Many states run their own drug assistance programs for residents who don’t qualify for federal programs or need help with cost-sharing. Check your state health department’s website for current offerings.
These programs tend to fill very specific gaps. Ryan White, for example, can cover HIV medications for someone who earns too much for Medicaid but can’t afford private insurance. The 340B program can reduce drug costs for a patient who is already receiving primary care at an FQHC. Knowing which programs overlap with your situation can meaningfully reduce your total out-of-pocket spending.
How do you find and apply for income-based care programs?
Getting connected to the right program is often the hardest part. Here’s a practical sequence that works for most situations.
- Screen for Medicaid and CHIP first — Go to HealthCare.gov and use the eligibility screener. It takes about 10 minutes and tells you whether you likely qualify for Medicaid, CHIP, or a subsidized Marketplace plan.
Commonly required documents
- Government-issued photo ID (driver’s license, passport, or state ID)
- Social Security numbers for all household members applying
- Recent pay stubs (last 30–60 days) or a current tax return
- Proof of residency (utility bill, lease, or bank statement)
- Documentation of any other income sources (self-employment, child support, Social Security)
If you lack some of these, don’t wait. Many programs accept self-attestation or alternative documentation. A community health worker or certified application assister can help you navigate gaps.
Pro Tip: Call 211 before you spend hours searching online. The 211 helpline connects you to a local specialist who knows which programs are currently accepting applications in your area, what the current wait times look like, and whether any local emergency funds are available. It’s free and available in most states.
How much does hospital charity care vary, and why does it matter?
The variation in hospital financial assistance policies is one of the most consequential and least-discussed features of the U.S. safety net. Peer-reviewed research in Health Affairs and confirmed in PubMed-indexed analysis documents just how wide that range is.
| Dimension | What the Research Found |
|---|---|
| Income cutoff for free care | Varies widely across nonprofit hospitals |
| Median free-care income cutoff | Around 200% of the Federal Poverty Level |
| Median discounted-care cutoff | Around 400% of the Federal Poverty Level |
| Asset tests | Many hospitals conduct asset reviews in addition to income screening |
| Residency requirements | Some hospitals limit FAP eligibility to local residents |
That spread has real consequences. A patient earning 250% FPL could receive free care at one hospital and owe the full bill at another, for the same procedure, in the same city.
Studies on financial assistance program impacts also show that fragmented financing and varied program reach affect how and whether patients use care at all. When patients don’t know a FAP exists, or assume they won’t qualify, they delay care or avoid it entirely, which tends to increase costs and worsen outcomes over time.
What to do when hospital policies work against you
- If you have a choice of hospital for non-emergency care, call the billing offices of two or three facilities and ask for their FAP income cutoffs before scheduling.
- If you’re already at a hospital with a restrictive policy, document your financial hardship in writing and ask whether the hospital has a hardship exception or a charity review board above the standard FAP.
- Contact a patient advocate or legal aid organization if you believe a nonprofit hospital is not complying with its Section 501® obligations. The IRS accepts complaints about nonprofit hospital tax-exempt status violations.
- USA.gov’s medical bill help guide outlines additional steps for negotiating bills and finding local assistance resources.
Key Takeaways
Income-based care programs in the U.S. span five distinct categories, and knowing which one fits your situation determines how quickly you can access affordable care and how much you’ll pay.
| Point | Details |
|---|---|
| Start with Medicaid or CHIP | Check eligibility at HealthCare.gov first; Medicaid covers most low-income adults in expansion states up to roughly 138% FPL. |
| Hospital FAPs are a legal right | Nonprofit hospitals must have a written financial assistance policy under Section 501®; always ask for it before paying a bill. |
| Charity care varies widely | Free-care income cutoffs range from 41% to 600% FPL across nonprofit hospitals (median around 200% FPL; discounted care median around 400% FPL), so the hospital you choose matters. |
| FQHCs serve everyone | Federally Qualified Health Centers offer sliding-fee care regardless of insurance or immigration status; find one via HRSA’s locator. |
| Chameleonhc fills the gap | For same-day care when eligibility is pending or wait times are long, Chameleonhc offers transparent telehealth pricing with no insurance required. |
Why program literacy changes outcomes for low-income patients
Most people who end up with medical debt didn’t know they had options. That’s the uncomfortable truth sitting behind the statistics on charity care and Medicaid enrollment. The programs exist. The legal protections exist. But they only work for patients who know to ask for them, know what documents to bring, and know how to appeal when something goes wrong.
There’s also a timing problem. Public programs like Medicaid can take weeks to process. Hospital FAP applications have deadlines. Free clinic slots fill up. For someone dealing with a sore throat, a rash, or a sinus infection that needs attention today, waiting for program approval isn’t always realistic. That’s where accessible, same-day options matter. Combining community resources with a low-cost telehealth visit for immediate needs can reduce unnecessary emergency room use and keep small health concerns from becoming larger ones.
Chameleonhc is built for exactly that kind of situation: clear pricing, no insurance required, and a licensed provider available the same day. It doesn’t replace Medicaid or an FQHC for ongoing care, but it can be a practical option while you work through the enrollment process or wait for your next clinic appointment.
Telehealth as an affordable option when public programs aren’t yet in place
Public income-based programs are worth pursuing, and this guide gives you the tools to do that. But eligibility takes time to confirm, applications take time to process, and health concerns don’t always wait. Chameleonhc offers a different kind of access: same-day telehealth visits with licensed providers, transparent upfront pricing, and no insurance required.
For common conditions like sore throats, sinus infections, rashes, and heartburn or reflux symptoms, you can connect with a provider from your phone or computer without a waiting room or a surprise bill. Membership plans make unlimited visits even more affordable for people who need care regularly. This isn’t a public assistance program and it doesn’t replace Medicaid when you qualify. Think of it as a practical option for the gap between “I need care now” and “my coverage is sorted out.”
If you’re uninsured and want to understand affordable telehealth care for uninsured patients, Chameleonhc’s model is worth a look. Visit chameleonhc.com to see current pricing and connect with a provider today.
This article provides general information about publicly available healthcare programs and is not a substitute for professional legal, financial, or medical advice. Program rules, income thresholds, and eligibility criteria change. Confirm current requirements directly with the relevant program or a qualified professional.
Authoritative resources for enrollment and program information
| Resource | What It Provides | When to Use It |
|---|---|---|
| HealthCare.gov | Medicaid/CHIP screener, Marketplace enrollment, subsidy calculator | First stop for any coverage question |
| Medicaid.gov | State-by-state Medicaid program details and contacts | When you need your specific state’s rules |
| HRSA Find a Health Center | Locator for FQHCs, migrant health centers, and RHCs | Finding sliding-fee primary care near you |
| NAFC Clinic Finder (nafcclinics.org) | Directory of free and charitable clinics | Finding volunteer-run free clinics |
| 211.org | Local social services and financial assistance referrals | Fastest way to find local program help |
| IRS Section 501® guidance | Legal requirements for nonprofit hospital FAPs | Understanding your rights with hospital billing |
| USA.gov medical bill help | Consumer steps for negotiating bills and appealing denials | After receiving a bill you can’t pay |